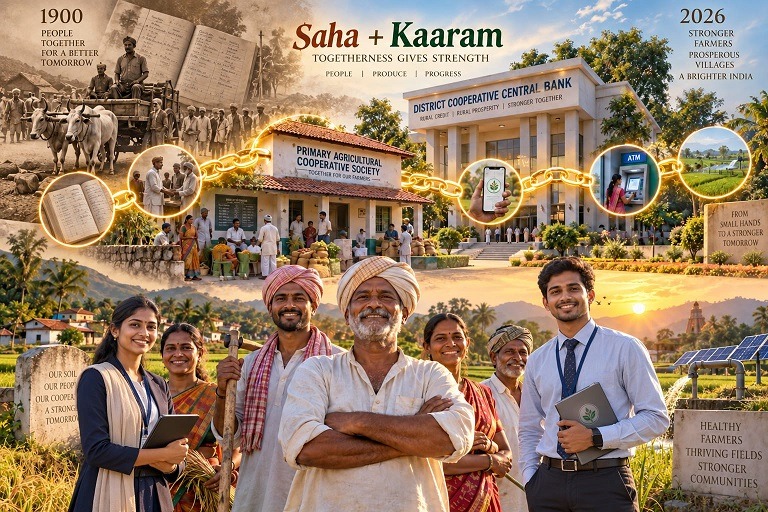
From the village credit societies of the early 1900s to the District Cooperative Central Banks of 2026, the cooperative movement has carried both softness and strength: the softness to stand with the farmer, and the strength to fight rural financial exploitation.
A commercial bank may see a farmer as an account number. A cooperative society sees him as a member. That difference is not small. It is the difference between a transaction and a relationship.
Editorial Article
KARIMNAGAR, SEPTEMBER 21, 2026: The Telugu language has a rare power. It can turn a common word into a social philosophy. One such word is “Sahakaaram”, meaning cooperation.
“Kaaram” means spice, sharpness, heat, and intensity. “Saha” means togetherness, support, companionship, and shared strength. When these two meanings come together, the result is not merely a pleasant word. It becomes a complete social idea.
Cooperation is not weakness. Cooperation is not charity. Cooperation is not a soft request for help. True cooperation has the warmth of togetherness and the sharpness of collective strength. It consoles the weak, but it also challenges the forces that make people weak.
That is why cooperative societies and District Cooperative Central Banks are not ordinary financial institutions. They are rural India’s emotional, economic, and social backbone. They stand between the farmer and financial helplessness. They carry credit, trust, discipline, and dignity into the village economy.
The Early 1900s: When Rural India Needed a Shield
At the beginning of the twentieth century, rural India was caught in a painful financial trap. The farmer depended on rainfall, soil, cattle, labour, and hope. But when he needed money, he often had to depend on the private moneylender.
That dependence was costly. Interest rates were high. Repayment conditions were harsh. A failed crop did not merely mean loss of income. It often meant debt, humiliation, sale of jewellery, distress sale of produce, and sometimes the loss of ancestral land.
It was in this background that the cooperative idea entered rural India. The basic principle was simple but revolutionary: people with similar needs could come together, pool trust, create an institution, and support one another.
The cooperative credit society was born as a rural answer to rural distress. It was not created as a luxury. It was created as a necessity. It was the poor man’s bank before formal banking reached the poor man’s street.
This was the first great meaning of Sahakaaram: ordinary people joining hands to protect themselves from extraordinary hardship.
The Village Cooperative Society: The Farmer’s First Financial Family
A Primary Agricultural Cooperative Society is not merely a counter where loan applications are received. It is a local institution rooted in the village. It knows the farmer, his land, his crop pattern, his family situation, his repayment capacity, and the risks he faces every season.
A commercial bank may see a farmer as an account number. A cooperative society sees him as a member. That difference is not small. It is the difference between a transaction and a relationship.
For generations, cooperative societies helped farmers with crop loans, fertilisers, seeds, agricultural inputs, and other village-level services. In many areas, they became the first formal institution through which rural people learned savings, credit discipline, collective responsibility, and democratic participation.
The cooperative society gave the farmer a voice. It made him not only a borrower, but a member. In this single change lies the moral power of the cooperative movement.
A borrower waits before a bank. A member belongs to an institution. That is the soul of cooperation.
District Cooperative Central Banks: The Strength Behind the Village Network
If the village cooperative society is the hand that reaches the farmer, the District Cooperative Central Bank is the arm that gives that hand strength.
District Cooperative Central Banks emerged as the crucial middle structure in the cooperative credit system. They connected village-level societies with higher financial institutions. They mobilised deposits, channelled funds, provided credit limits, monitored societies, ensured recovery discipline, and supported agricultural finance across the district.
The DCCB became the district-level guardian of cooperative credit. Its role was not limited to lending money. It had to understand agriculture, seasons, local economics, rural psychology, village institutions, government schemes, and the repayment behaviour of thousands of farmers.
It had to balance compassion with discipline. It had to support PACS while also correcting them when required. This is where the “kaaram” of cooperation becomes visible.
A cooperative bank cannot survive only on emotion. It needs recovery, audit, governance, transparency, staff discipline, professional management, and responsible leadership. Without these, cooperation becomes sentiment without strength. With these, cooperation becomes a movement with muscle.
The Fierce Bond Between PACS and DCCBs
The relationship between cooperative societies and District Cooperative Central Banks is not a casual institutional link. It is a deep rural financial bond created by history, necessity, and public trust.
PACS take the bank to the farmer. DCCBs take financial strength to PACS. PACS understand the ground. DCCBs organise the system. PACS carry local trust. DCCBs carry district-level credibility. PACS distribute credit. DCCBs protect the credit structure.
One without the other becomes incomplete. If PACS are weak, the DCCB cannot effectively reach the farmer. If the DCCB is weak, PACS cannot stand financially. Their relationship is like soil and seed. The seed cannot grow without soil. The soil cannot fulfil its purpose without seed.
This bond is a “ghaataina anubandham” — a sharp, intense, inseparable relationship. It is the bond between the village and the district, between member and institution, between local need and organised finance.
Cooperation as Democracy in Daily Life
The cooperative movement also gave rural India a school of democracy. In a cooperative society, members elect representatives. They attend general body meetings. They question accounts. They discuss credit, recovery, business, and service. They learn that institutions belong not to distant rulers, but to participating members.
For many rural leaders, cooperatives became the first platform of public life. Before entering higher politics, several leaders across India learned public dealing, accountability, negotiation, and grassroots mobilisation through cooperative institutions.
This is one of the least understood contributions of the cooperative movement. It did not merely lend money. It trained villages in democratic behaviour. A cooperative election may look small to outsiders, but in rural India it often teaches the first lesson of public leadership.
After Independence: A Nation Built Through Rural Credit
After Independence, India had to feed itself, finance agriculture, and protect millions of small and marginal farmers. Rural credit became a national priority. Cooperative credit institutions became a natural instrument for this responsibility.
Through crop loans, seasonal agricultural operations, medium-term loans, input supply, and rural financial support, cooperative banks and societies became essential to India’s agricultural journey.
They stood with farmers through droughts, floods, price fluctuations, pest attacks, and market uncertainties. When agriculture needed institutional credit, cooperatives were already present in the village. When the farmer needed a local institution, PACS were already there. When PACS needed financial support, DCCBs were the connecting force.
This is why the cooperative credit structure became more than a banking arrangement. It became a public rural infrastructure. Roads connect villages physically. Schools connect them socially. Cooperative banks connect them economically.
The Tests of Time: Weaknesses That Cannot Be Ignored
No honest editorial can speak only of glory. The cooperative movement also faced serious weaknesses. In many places, governance weakened. Elections were delayed. Professional management was neglected. Political influence affected institutional discipline. Some societies became inactive. Recovery culture suffered. Technology adoption was slow. Audit objections accumulated. Staff shortages affected service quality.
These problems did not arise because cooperation is a wrong idea. They arose because cooperation requires constant discipline.
A cooperative institution is like a living crop. It cannot be planted once and forgotten. It needs watering, supervision, protection, and timely harvesting. Similarly, cooperatives need elections, audits, member participation, recovery, transparency, training, technology, and honest leadership.
Without governance, cooperation becomes weak. Without recovery, credit becomes charity. Without transparency, trust disappears. Without member participation, democracy becomes only a file record. Therefore, the future of cooperation depends not on emotional praise alone, but on institutional correction.
The 2000s and Beyond: From Survival to Renewal
The period after 2000 forced cooperative institutions to rethink their role. Banking changed. Technology entered every financial transaction. Customers expected speed, transparency, digital access, and professional service. Rural youth became more educated. Farmers became more market-aware. Government schemes increasingly moved through digital platforms.
In this new environment, cooperative banks could not remain only traditional institutions. They had to modernise. Core banking, digital payments, mobile alerts, ATM services, online monitoring, professional audit systems, recovery tracking, and better human resource management became essential.
A DCCB that wants to serve the farmer of 2026 cannot function with the tools of 1976. At the same time, modernisation should not destroy the cooperative soul. Technology must strengthen the member relationship, not replace it. Digital banking must make PACS more efficient, not make them irrelevant.
The correct future is not technology instead of cooperation. The correct future is technology in the service of cooperation.
PACS in 2026: From Credit Societies to Rural Development Centres
The biggest opportunity before India in 2026 is to transform PACS into multi-service rural institutions. A PACS should not be limited to crop loans alone. It can become a centre for fertilisers, seeds, warehouses, cold storage, custom hiring centres, food processing, dairy support, marketing, rural retail, digital services, insurance facilitation, and support to women’s self-help groups.
The village economy is no longer only about cultivation. It is about value addition, storage, marketing, processing, women’s entrepreneurship, youth employment, and connecting the farmer to markets with dignity.
If PACS expand in this direction, DCCBs must become their strategic financial partners. They must guide them, finance them carefully, monitor them professionally, and protect them from unviable ventures.
The new cooperative model must be ambitious, but not reckless. It must be bold, but not careless. That is again the meaning of Sahakaaram: soft heart, sharp mind.
DCCBs in 2026: The Need for Professional Strength
District Cooperative Central Banks today carry a heavier responsibility than ever before. They must compete with commercial banks, comply with regulatory expectations, support PACS, protect depositors, serve farmers, maintain profitability, reduce NPAs, adopt technology, and improve governance.
This requires professional boards, trained staff, strong internal controls, timely audits, effective recovery systems, and clear accountability. The DCCB of the future must be both cooperative and professional. It must not lose its rural character, but it must also not ignore modern banking standards.
A cooperative bank cannot say, “We are cooperative, so discipline is optional.” A cooperative bank must say, “Because we are cooperative, discipline is even more important.”
Public trust is sacred. Depositors’ money is sacred. Farmers’ hopes are sacred. Staff responsibility is sacred. Therefore, governance must be sacred too.
Why This Bond Still Matters
In the age of commercial banks, Fintech companies, mobile banking, and private finance, some may ask why cooperative banks still matter. The answer is simple: rural India needs institutions that understand rural life.
A farmer’s financial life is not like a salaried employee’s financial life. His income is seasonal. His risks are natural. His repayment depends on crop, weather, market price, input cost, and family emergencies. His need is not only credit; his need is understanding.
Cooperative institutions, when properly governed, are uniquely placed to provide that understanding. They are local. They are member-based. They are democratic. They are connected to agriculture. They are rooted in the soil.
India does not need to abandon cooperatives. India needs to rebuild them.
The Way Forward: Reform Without Losing the Soul
The cooperative movement from 1900 to 2026 teaches one clear lesson: institutions survive when they remain useful, honest, and close to people.
For the future, PACS must be strengthened as village-level economic centres. DCCBs must be strengthened as district-level cooperative banking pillars. Elections must be regular. Boards must be responsible. Professionals must be included. Staff must be trained. Technology must be adopted. Recovery must be improved. Women and youth must be brought into the cooperative fold. Members must be educated about their rights and duties.
Government support is important. Regulatory guidance is important. NABARD and higher cooperative institutions are important. But finally, the strength of cooperation must come from members themselves.
A cooperative society is not strong because it has a building. It is strong because members believe in it. A DCCB is not strong because it has branches. It is strong because PACS, farmers, depositors, staff, and leadership trust it. Trust is the capital of cooperation.
Conclusion: The Word That Became a Rural Heartbeat
“Kaaram” gives sharpness. “Saha” gives togetherness. Together, they become “Sahakaaram.” This single word contains the history of rural India’s struggle, survival, and strength.
For more than a century, cooperative societies and District Cooperative Central Banks have stood between the farmer and financial helplessness. They have carried credit to the village, dignity to the member, discipline to rural finance, and hope to agriculture.
They were born in a time of distress. They grew through collective trust. They survived through public faith. They now stand at a turning point.
If they remain only old institutions, they may slowly weaken. But if they renew themselves with governance, technology, professionalism, member participation, and rural vision, they can become the strongest foundation of India’s next rural economic revolution.
The cooperative movement is not a closed chapter. It is an unfinished promise. It is the promise that no farmer should stand alone. It is the promise that no village should remain financially voiceless. It is the promise that money can have morality when people own the institution. It is the promise that development can be democratic.
That is why cooperation is not just a policy word. It is not merely banking. It is not merely credit. It is rural India’s heartbeat.
When that heartbeat is strong, the village stands. When the village stands, the farmer stands. When the farmer stands, the nation stands.
Cooperation is the softness of “Saha” and the sharpness of “Kaaram.” It is compassion with courage. It is service with discipline. It is the farmer’s bank, the village’s strength, and the nation’s rural soul.
About the Author