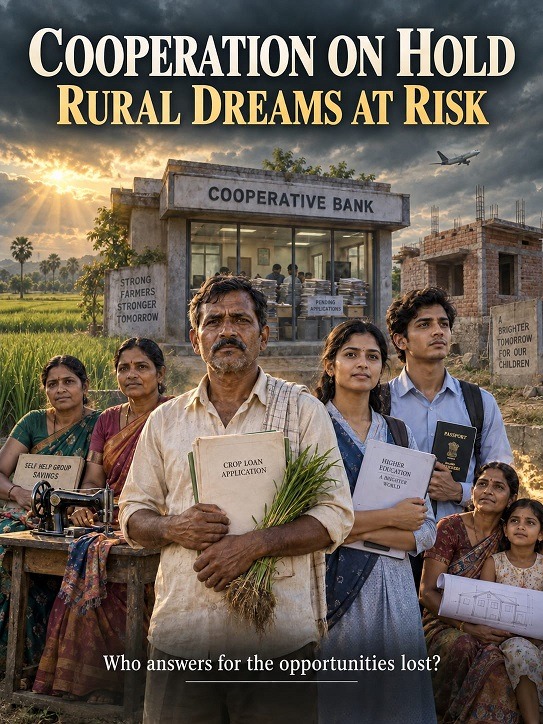
When crop credit stalls and loans for education, housing and women’s livelihoods face hurdles, who will answer for the opportunities lost?
KARIMNAGAR, SEPTEMBER 24, 2026: A farmer cannot plant an assurance. A student cannot pay a university with a pending application. For families who depend on cooperative credit, the time taken to make a lending decision can determine whether an opportunity survives. Decisions taken without sufficient thought, or postponed without explanation, can turn an institution of support into a source of uncertainty.
The concerns raised about crop loans, overseas education finance, housing loans and credit for self-help groups deserve a clear public response. Their extent and causes must be established through the relevant records. They should not be treated as proof that every cooperative institution has stopped lending, or that every restriction is unjustified. The central demand is straightforward: explain what is happening, identify who can resolve it and ensure that eligible members receive timely decisions.
If administrative confusion is preventing sound lending, the authorities concerned must correct it. If financial or policy constraints require limits, members should be told what those limits are and why they exist. Cooperation loses credibility when the people it serves are left to guess.
The Farmer Cannot Sow a Pending File
Rain does not wait for an administrative clarification. Once the sowing window opens, a farmer needs seed, fertiliser, labour and money. A crop loan that arrives after the critical stage may have lost much of its purpose. The time taken to decide an application is therefore part of the quality of the service itself.
Consider a farmer who is repeatedly told that a proposal has been forwarded or that instructions are awaited. The office may record an application as pending. At home, the farmer must decide whether to postpone cultivation, reduce the acreage or borrow elsewhere at a higher cost. Administrative delay can become a private debt burden.
Eligibility checks and repayment assessment remain necessary. They should be completed through a process that respects the agricultural calendar. Missing documents should be identified promptly, lending conditions explained in advance, and responsibility for the decision clearly assigned. A farmer should know when an answer will come.
A system that recognises the due date for repayment must also recognise the date by which credit is needed.
A Delayed Education Loan Can Close a Door Forever
For a rural student, admission to an overseas institution can represent years of preparation and a family’s careful savings. Studying abroad is not, by itself, evidence of wealth. For an eligible student from an ordinary household, an education loan may determine whether the opportunity can be taken up at all.
The institution, course, costs, repayment prospects and applicable lending policy deserve careful scrutiny. But scrutiny needs a clear procedure and a reasonable timetable. Admission deadlines and fee schedules do not automatically change because a lending decision remains unresolved.
If an overseas education loan product is restricted, revised or unavailable, applicants should receive a clear explanation. They should be told how pending applications will be treated and whether any permissible alternative exists. Silence leaves a family unable to plan, while repeated verbal assurances can create expectations that the institution cannot fulfil.
A student can respond to a stated condition. It is far harder to respond to an unexplained wait that ends only when the admission deadline has passed.
When Housing Credit Stops the Household Pays
A modest home is often built through a combination of savings, borrowed funds and years of sacrifice. When a housing loan application remains uncertain, or a sanctioned instalment is delayed despite the relevant conditions being met, construction can stall at the most expensive stage.
An unfinished structure may leave the family paying rent while managing construction commitments. Materials can deteriorate, labour arrangements can break down and restarting work may cost more. The consequences extend well beyond the amount of the pending instalment.
Property records, permissions, income and repayment capacity must be examined carefully. Applicants should nevertheless receive a complete list of requirements and an accurate account of their application’s status. Where disbursement depends on construction progress or another condition, the lender should explain exactly what remains outstanding.
A timely refusal with reasons allows a household to reconsider its plans. Indefinite uncertainty makes sensible planning almost impossible.
Do Not Make Women’s Independence Wait at the Counter
For a women’s self-help group, a loan may finance a sewing machine, dairy activity, a small shop or food production. These are practical efforts to earn an income and strengthen a family’s financial security. Even a modest amount can matter greatly when it arrives at the right time.
Groups that save regularly and accept collective repayment responsibility deserve a fair assessment under the applicable scheme. Their track record, proposed activity and ability to repay should guide the decision. Weaknesses in one application should be identified and addressed; they should not become an unexplained reason for holding up unrelated, eligible proposals.
Where support is delayed, a business may never open or a seasonal sales opportunity may disappear. The loss is then borne by women who were prepared to work, save and repay. Public praise for women’s empowerment carries little weight if the financing process leaves them without a clear answer.
Financial independence grows through dependable opportunities. Institutions should measure their contribution by the eligible enterprises they help to start and sustain.
When Rules Become a Maze Trust Begins to Break
The angry description of departmental functioning as a “sleight of hand that even cooperative experts cannot understand” points to a serious concern: decisions may appear impossible to follow. Conflicting explanations, unclear authority and repeated referrals between offices can make an ordinary member feel powerless.
That criticism should lead to scrutiny of records and decisions. It should not become a blanket accusation against every employee of the Cooperation Department. Frontline staff may themselves be waiting for instructions or working within powers they cannot expand. Many may be trying to resolve the very problems for which they face public anger.
The proper questions are specific. What instruction applies? Who issued it? Why was it necessary? Which loan categories does it affect? Who can clarify it, and when will it be reviewed? An institution that supplies these answers leaves less room for rumour and suspicion.
The public should not need an expert interpreter to discover why a loan application has stopped moving. Explaining a decision is part of administering it responsibly.
Protect the Depositor Without Abandoning the Borrower
Cooperative lending institutions handle money entrusted to them by depositors. Loan quality, recovery, liquidity and sound appraisal matter. Lending beyond a borrower’s capacity or an institution’s financial strength can harm the very members whom cooperation is meant to serve.
The case for timely credit is therefore a case for competent lending. Where restrictions are necessary, their reasons and scope should be explained through the appropriate channels. Management should identify the weakness being addressed and the conditions under which the position can be reviewed.
Different products create different risks. Crop finance, overseas education loans, housing loans and group lending need assessments suited to their circumstances. Any broad restriction should have a demonstrable basis, with its effects on eligible members considered before and during implementation.
Prudence requires judgement. Leaving every difficult application undecided does not, by itself, establish that an institution is being well managed.
The So Called Free Gifts Carry a Heavy Price
To call blocked opportunities the Cooperation Department’s “free gifts” is bitter satire. The phrase captures a member’s frustration when an institution created to provide support appears unable to respond. It must not substitute for establishing where delays have occurred or which authority is responsible.
The possible costs, however, are easy to understand. A farmer may pay more for alternative credit. A student may lose an admission opportunity. A family may face additional construction expenses. A women’s group may lose the chance to begin earning.
These costs rarely appear beside the words “awaiting clarification” in a file. A meaningful review should therefore ask how long an application has waited, what deadline the applicant faces and whether an avoidable delay has reduced the usefulness of the loan.
Public administration becomes remote from public life when it counts pending files without considering the people waiting behind them.
Responsibility Must Reach the Desk That Holds the Power
Who is responsible? The answer must follow the evidence and the power to act. A vague reference to “the system” allows everyone to share the explanation while no one accepts the task of correcting it.
If the problem lies in an unclear policy, the authority responsible for that policy should clarify it. If administrative arrangements leave institutions uncertain about who can decide, the government and the authorities concerned should resolve that uncertainty. Where funding or liquidity planning is deficient, management should explain the position and prepare a workable response.
If an application has been left idle despite complete documentation and available authority, the relevant level should account for the delay. If a branch has escalated a problem, the next level should record what action it took. An acknowledgement that a letter was received is not evidence that the problem was addressed.
Accountability should also protect employees who act properly within their authority and document genuine obstacles. Blaming the person at the counter while leaving the decision-making level unexamined would conceal the source of the failure.
An avoidable failure to decide deserves examination alongside an incorrect decision. Both can cause harm, although responsibility in any particular case must be established from the record.
Let the Public See What Is Pending and Why
The first corrective step should be an accurate review of applications across the affected loan categories. It should show how many were received, sanctioned, rejected and left pending, together with the age and main reasons for pending cases. Information made public should protect applicants’ personal and financial details.
The review should distinguish incomplete applications from those awaiting appraisal, funds, policy clarification or approval. Each category needs a responsible officer and a realistic period for action. Without that distinction, a large total of pending applications explains very little.
Time-sensitive cases deserve attention within the applicable rules. Agricultural seasons, admission deadlines and the conditions of already sanctioned construction loans should inform the order of review. Applicants should receive clear updates and a usable route for raising unresolved concerns.
Where authority is disputed or unclear, written clarification should identify who can decide and what must be referred elsewhere. Subsequent reviews should record actual outcomes: cases resolved, reasons for decisions and obstacles still requiring intervention.
The measure of progress is the quality and timeliness of decisions. A meeting held, a letter forwarded or a reminder issued cannot serve as the final answer to a member waiting for service.
Move the Life Behind the File
Cooperation rests on a promise that collective strength can help ordinary people meet needs they cannot easily manage alone. That promise is tested when a farmer seeks cultivation finance, a student needs support for education or a household hopes to build a secure home.
The concerns raised here call for facts, clear decisions and corrective action. They do not justify reckless lending or indiscriminate blame. They justify asking whether the institutions concerned are using their powers competently, explaining their constraints honestly and treating members’ time as valuable.
When an eligible application is held up by an avoidable administrative obstacle, the duty is to remove that obstacle. When a loan cannot responsibly be granted, the duty is to say so with reasons. In either case, the member deserves an answer that makes the next step possible.
The question “Who is responsible?” should finally lead to a named responsibility, a deadline and a visible improvement in service. Rural families cannot cultivate a field, secure an admission or complete a house with assurances alone.
It is not enough to say that the file has moved. The life waiting behind it must be able to move forward.
About the Author