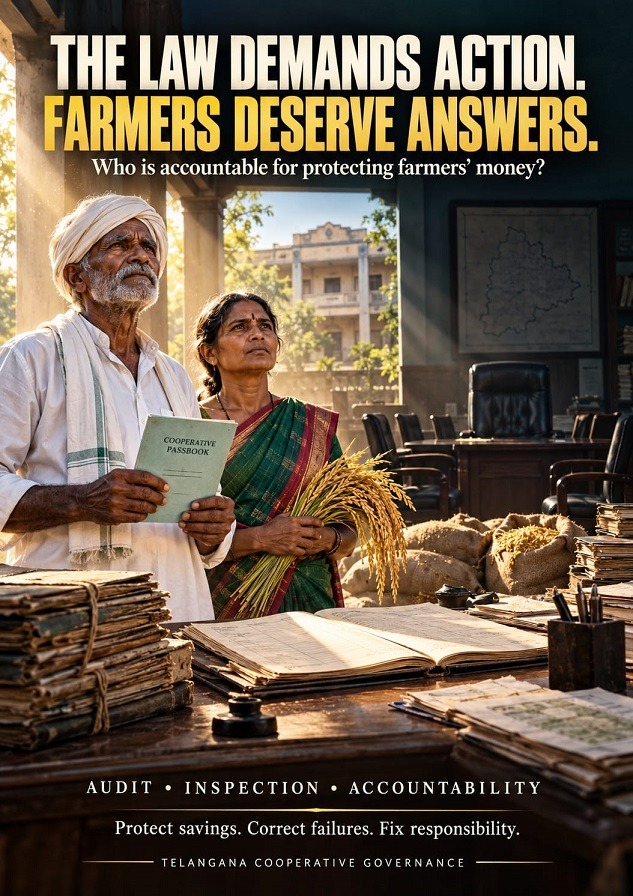
Telangana’s cooperative institutions need honest management and effective supervision. When money is put at risk, accountability must reach the society, the board and every authority responsible for oversight.
A farmer must explain an unpaid loan. A society employee must explain a missing amount. An elected board must explain a disputed decision.
Who asks the supervising officer what was checked, what was reported and what action followed?
KARIMNAGAR, OCTOBER 15, 2026: This question must become central to the debate on Telangana’s cooperative institutions.
These institutions hold farmers’ savings, members’ contributions and resources needed for rural livelihoods. When something goes wrong, the cost may fall on people who neither approved the transaction nor benefited from it.
The law provides for audit, inquiry, inspection and correction of defects. Government orders establish review committees and financial controls. The essential question is whether these safeguards work when members need them.
A failure by management does not excuse failed supervision. Failed supervision does not excuse wrongdoing by management. Both must be examined.
PUBLIC MONEY MUST PRODUCE PUBLIC SERVICE
Government departmental salaries are paid from the State treasury, supported by public revenue, including taxes. Citizens are entitled to ask what protection this expenditure delivers.
How many serious defects were corrected? How many complaints were resolved? What losses were prevented? What happened when directions were ignored?
Exact expenditure figures must come from official accounts. Accountability does not depend on making an unverified claim about how many crores are spent.
The distinction between establishments is also important. Government Cooperation Department employees, PACS employees and cooperative bank employees have different employers, duties and service arrangements.
G.O.Ms.No.44, dated December 17, 2022, concerns the human resource policy for Primary Agricultural Cooperative Societies—PACS. Its salary arrangements do not make all PACS employees government employees paid directly from the treasury.
But every institution in this structure owes an explanation for the responsibility entrusted to it.
DHARMAPURI: A TRANSACTION THAT NEEDS A COMPLETE ACCOUNT
An ‘Uppu News’, a vernacular daily report dated October 15, 2026, raises questions about a land purchase by Dharmapuri Single Window Society. It reports a resolution to purchase one acre, while 27 guntas in Survey No.84E were registered on July 6, 2020, through Document No.4052/2020. It also reports expenditure of ₹5,10,662 recorded for the 27-gunta purchase and associated charges.
According to complainants cited in the report, questions over the remaining 13 guntas remained unresolved despite earlier complaints. They later approached the Anti-Corruption Bureau, and money relating to that portion was deposited into the society’s account in September. The report also records allegations about attempts to submit an explanation favourable to the board, while acknowledging that official responses and inquiry findings are needed. These are reported claims, not established findings of guilt. [1]
The proper response is to examine the purchase records, payments, ownership documents and handling of complaints. Any verified repayment must be considered alongside the original transaction, the period involved and any established financial loss. Repayment alone cannot establish either innocence or guilt.
SECTION 50: AN AUDIT MUST EXAMINE WHAT THE SOCIETY OWNS AND OWES
Section 50 of the supplied text of the Telangana Cooperative Societies Act, 1964, provides for accounts to be audited within six months of the close of the financial year.
The audit covers matters including overdue debts, cash balances, securities, assets, liabilities, receipts and expenditure. It also includes administrative examination of prudent management.
These duties require meaningful work.
If money was paid for an asset, what did the institution receive? If an amount remains recoverable, what steps were taken? If expenditure lacks proper support, was that reported? If the books and bank statements differ, was the difference investigated?
The Act provides different audit arrangements, including departmental and qualified external auditors, depending on the applicable circumstances. Responsibility must therefore be traced to the auditor actually appointed and the work required.
An audit cannot guarantee that every concealed fraud will be discovered. But it must demonstrate that the required examination was performed.
A certificate is the result of an audit. It cannot replace the audit itself.
EVEN THE AUDIT CAN BE EXAMINED
The supplied text of Section 50(8) contains a further safeguard.
Where discrepancies or deviations are noticed in audit procedures or an audit certificate issued by a Chartered Accountant or firm, it provides for the Government, on the Registrar’s recommendation, to order a test audit by the Chief Auditor and take necessary action as specified.
This provision should not be stretched beyond its stated scope. It nevertheless answers an important question: the issue of an audit certificate need not end scrutiny of the audit’s quality.
Where serious concerns arise, the competent authority should examine the appropriate review mechanism and record its decision.
“The accounts were audited” is not a complete answer to evidence that requires further examination.
SECTION 54: A DEFECT RECORDED MUST LEAD TO FOLLOW-UP
Section 54 addresses defects found during audit, inquiry or inspection.
The supplied text requires the Registrar to bring those defects to the society’s attention and, where applicable, to the attention of its affiliated society. It permits directions requiring corrective action within three months and provides for a prescribed penalty where audit defects are not rectified within three months.
This makes repeated objections a matter of accountability.
Was the defect formally communicated? Was a correction ordered? Was a deadline given? Did management respond? Was the claimed correction verified? What happened when nothing changed?
The society must explain its failure to correct the defect. The supervisory authority must explain its follow-up.
An objection copied from one annual report to the next may preserve a record. It does not protect the institution unless action follows.
INSPECTIONS NEED EVIDENCE, NOT MERELY ENTRIES
Did the officer actually visit? Was cash physically checked? Were stocks verified? Were records compared with independent supporting documents? Does the report show the work performed?
These questions distinguish a meaningful inspection from a paper exercise.
Section 52 provides a three-month period for completing an ordered inspection from the inspecting officer’s receipt of the order, with a limited extension for recorded reasons. This is a completion deadline; it is not a general requirement to inspect every society once every three months.
Routine inspection frequency must be checked against the separate instructions that apply. Section 51 likewise provides a time frame for inquiry, with a limited extension.
Once a report is submitted, accountability moves to the next level.
Who received it at the district office? Who examined it? Was it referred to the State authority where necessary? Who was required to act?
A warning that passes through several offices without a response requires examination of the entire chain.
MEMBERS MUST KNOW WHAT THE REPORT FOUND
Sections 51 and 52 provide for inquiry and inspection reports, with the Registrar’s findings, to be communicated to the managing committee. The committee must place them before the general body or a special general body within the prescribed one-month period after communication.
The institution belongs to its members. Serious findings concerning their money should not remain hidden in an administrative file.
Placing a report before members does not remove the Registrar’s power to take necessary follow-up action.
Disclosure and enforcement are separate responsibilities. Neither can substitute for the other.
THE FINANCING BANK ALSO HAS A DEFINED ROLE
Section 53 provides a financing bank or federal society with a right to inspect the books of a society indebted to it, through the authorised arrangements described in the provision.
This right has a defined scope. It should not be presented as unlimited authority over every society, regardless of its relationship with the bank.
Where the provision applies, however, the bank’s inspection role should also be examined. What information was obtained? What risks to the funds lent were identified? What action followed?
The department, financing bank, auditor and managing committee perform different functions. Effective protection depends on each doing its own work and communicating significant findings.
A divided responsibility must not become a responsibility that nobody accepts.
G.O.44: REVIEW COMMITTEES MUST SHOW RESULTS
G.O.Ms.No.44 establishes a State Level Empowered Committee—SLEC—and a DCCB Level Empowered Committee—DLEC—for implementation of the PACS human resource policy.
The supplied copy provides for SLEC meetings at least quarterly and DLEC meetings at least once in two months.
These bodies are not substitutes for statutory audit or investigation. Their assigned duties nevertheless include important reviews linked to policy implementation.
DLEC responsibilities include reviewing PACS imbalances and non-performing assets, facilitating timely audit, and obtaining and reviewing audited data by September before forwarding it to the State level. SLEC responsibilities include obtaining that data through DLECs by October, analysing it and advising on performance.
Were these meetings held? Was the information received? Were unresolved weaknesses identified? What decisions were taken? Were those decisions implemented?
Minutes should record more than attendance. They should allow members and competent authorities to understand what the review achieved.
DAILY CONTROLS MUST PREVENT YEARS OF CONFUSION
The implementation provisions in the supplied G.O.44 include daily computerised account closure, remittance of cash receipts within 48 hours subject to the prescribed cash-retention arrangement, and submission of monthly trading and stock information.
They also provide for a salary margin account and periodic monitoring.
Where these requirements apply, an irregularity should prompt examination of the particular control that failed.
Was information not submitted? Was it submitted but not checked? Was a difference identified but left unresolved?
Sundry and suspense accounts require the same discipline. These accounts can contain amounts awaiting identification or adjustment. Their existence does not automatically establish fraud. But old, unexplained balances weaken the reliability of the accounts.
Reconciliation means comparing records and explaining differences. Each unresolved amount should have supporting documents, an assigned responsibility and a completion date.
Overdue loans also require active review. Genuine hardship, missing documents, legal obstacles and avoidable delay need different responses, supported by a fair recovery plan.
PROCUREMENT CHARGES MUST HAVE AUTHORITY AND ACCOUNTS
Paddy procurement requires clear records of purchases, deliveries, payments and outstanding amounts. Gunny-bag accounts must explain receipts, use, returns and closing stock.
Differences between society records, bank statements and procurement-agency accounts should be resolved promptly.
Where supervision or administrative charges are collected, the relevant order or agreement, the amounts collected and their use should be established. G.O.44 should not be treated as automatic authority for every procurement-related charge.
Members are entitled to know what service their institution received in return.
Where a shortage is established, responsibility should be examined both at the transaction level and at the level specifically entrusted with verification and follow-up.
Supervision must be visible in the records and the action taken—not merely in the charge collected.
REINSTATEMENT MUST REST ON REASONS, NOT INFLUENCE
G.O.44 sets out disciplinary and appellate arrangements for PACS employees. Depending on the employee category and the action involved, it assigns roles to society authorities, DLEC and SLEC.
For Secretary and Staff Assistant categories, the supplied table distinguishes specified major penalties from removal, dismissal and compulsory retirement. It assigns different decision, consultation and appeal roles. A particular order must therefore be examined against the correct route.
An employee may return to service following an appeal, a court order, an unproved charge or a procedural defect. Reinstatement alone does not prove favouritism.
But the decision must be reasoned. If a loss was established, recovery and safeguards remain relevant questions.
Allegations that cases were deliberately weakened require examination of the provisions considered, evidence collected, documents submitted and reasons recorded. A case failing does not itself prove collusion.
Procedural fairness must protect the innocent. It must not become a cover for deliberate interference.
REMOVING A BOARD DOES NOT COMPLETE ACCOUNTABILITY
Section 31-A assigns the managing committee duties relating to audit, presentation of reports, correction of defects and review of outstanding loans and recovery action.
An elected mandate does not excuse wrongdoing. Nor does removal of a board explain failures elsewhere.
Who approved the transaction? Who executed it? Who recorded dissent? Who checked it? Who received the complaint? Who could have intervened?
The answers must distinguish the responsible from the innocent.
Section 60 provides for surcharge proceedings in specified circumstances, including misappropriation, fraudulent retention, breach of trust, wilful negligence and improper payments. Its conditions and the opportunity to respond must be respected.
It should not be claimed that every government inspector automatically falls within that provision. Departmental negligence may require proceedings under applicable service rules; evidence of criminal conduct requires examination under the relevant law.
Societies registered under the 1995 Mutually Aided Cooperative Societies Act also require separate attention. That Act has its own audit, special-audit, inquiry and follow-up provisions.
Firm action requires the correct law, clear evidence and individual responsibility.
INNOCENT MEMBERS MUST NOT PAY FOR INSTITUTIONAL FAILURE
A farmer awaiting a legitimate loan, an employee with no role in a disputed transaction and a member who voted in good faith should not be treated as responsible for someone else’s misconduct.
Prolonged uncertainty can delay services, damage confidence and weaken an institution’s reputation.
Investigations must proceed while essential lawful services continue. Action against individuals must be based on their conduct. Restoration of sound governance must remain a clear objective.
An energetic officer who improves follow-up deserves support, adequate staffing and clear authority. Allegations of internal resistance should be tested against evidence. Reasonable performance standards should not be abandoned merely because they disturb familiar habits.
The system must work beyond the tenure of one effective officer.
TELANGANA NEEDS CORRECTION, DISCLOSURE AND CONSEQUENCES
The State should require an institution-wise review of unresolved audit objections, incomplete asset transactions, unsettled procurement accounts, old unexplained balances and pending recovery action.
Each significant matter should have a responsible authority, a deadline and a recorded outcome. Where supervisory conduct is itself questioned, the review should have sufficient independence.
Honest officials and employees should be protected. Proven misconduct should attract appropriate action at every level. Members should receive understandable information about their institutions.
The promise of Bangaru Telangana must reach the farmer’s society through reliable accounts, timely decisions and money protected.
Farmers deserve safeguards before their savings are lost—not merely explanations afterwards.
The law has assigned duties. Government orders have created review mechanisms. Every authority must now answer the same question: what did you do with the responsibility entrusted to you?
SOURCE REFERENCES
- Uppu News, October 15, 2026: https://uppunews.com/2026/10/flashacbentrytho-dharmpuriwindowbhumilokdhlika/
- Telangana Cooperative Societies Act, 1964, and Telangana Mutually Aided Cooperative Societies Act, 1995: supplied compilation, “1964 Act & MACS Act Final RCS.pdf”.
- G.O.Ms.No.44, Agriculture and Cooperation Department, dated December 17, 2022: supplied Telugu-converted copy, “GO MS 44 Telugu Converted.pdf”.
About the Author